5 Exemplos Do Uso Da Matemática No Dia A Dia

Math doesn't show off in daily life, but it is everywhere if you actually look at what you are doing.
Most people think math is something you learned in school and then forgot. That is wrong. You use it constantly without giving it a second thought. The trick is learning to recognize the patterns so they stop being abstract and become practical tools.5 exemplos do uso da matemática no dia a dia
1. Calculating discounts while shopping When you see a sign that says 30% off, you need to figure out the real price fast. A lot of people struggle with this at the register. The quick method is to find 10% first by moving the decimal one place to the left, then multiply by 3. On a R$ 89.90 item, 10% is R$ 8.99. Times 3 is R$ 26.97. Subtract that from the original price and you get R$ 62.93. I once watched someone pay full price because they panicked over the mental math at a busy store checkout. Do not be that person. Learn this once and save yourself from bad deals. 2. Cooking and recipe scaling
Recipes are basically math problems disguised as instructions. If a recipe serves four and you need to feed six, you are doing ratios. Multiply every ingredient by 1.5. If a recipe calls for 200 grams of flour and you need to halve it, that is 100 grams. I spent an entire evening once making cookies because I miscalculated the scaling factor and ended up with triple the dough. I threw most of it out. The lesson was simple: write down your multiplier before you start touching ingredients. 3. Managing your monthly budget Tracking income and expenses requires basic arithmetic, but the real skill is allocation. The 50-30-20 rule divides your net income into needs, wants, and savings. If you earn R$ 4,000, that means R$ 2,000 for essentials, R$ 1,200 for discretionary spending, and R$ 800 saved. Most people skip this and wonder where their money goes. I kept a spreadsheet for three years and it revealed patterns I never would have noticed. Certain subscriptions were draining R$ 180 a month that I barely used. Canceling them freed up enough for an extra emergency fund payment.
4. Estimating travel time and fuel costs Planning a road trip or even a commute involves distance divided by speed. If you are driving 240 kilometers at an average of 80 km/h, the trip takes three hours. For fuel, divide your distance by your car's consumption rate, then multiply by fuel price per liter. A car that does 12 km per liter driving 240 km uses 20 liters. At R$ 5.80 per liter, that is R$ 116.00. I underestimated a weekend trip once and ran halfway through fuel money because I did not account for city driving lowering my average consumption. Always add a 15% buffer to your estimates. 5. Understanding interest on loans and savings

This is where math separates the careful from the careless. Compound interest works both for you and against you. A savings account yielding 10% annually compounded monthly will grow your money significantly faster than simple interest. Conversely, credit card debt at 14% monthly compounded daily can destroy your finances. I paid off a R$ 5,000 personal loan early and saved approximately R$ 800 in interest by switching to a smaller rate loan first. The math was clear: every month of delay cost me real money. Use an amortization schedule calculator online if you want to see the exact breakdown before signing anything.
The hard part is not knowing the formulas
The formulas are easy to look up. The difficulty is recognizing which one applies to your situation in real time. I have seen people freeze when asked to split a restaurant bill evenly among six friends including tax and tip. The solution is straightforward: add the bill plus 10% tax, add 15% tip on the subtotal, then divide by six. On a R$ 360 bill, that comes to about R$ 76.50 per person. Nothing magical about it, just practice. Another common blind spot is percentage change. When your electricity bill jumps from R$ 180 to R$ 234, that is not just "a bit more." It is a 30% increase. People miss this because they focus on the raw number difference instead of the relative change. Tracking percentage changes over time on recurring expenses gives you early warning signs before small problems become expensive ones.
There are cases where mental math fails you
Complex loan comparisons with varying interest rates and fee structures are one of those cases. I tried doing a multi-variable calculation in my head once comparing two financing options and ended up with two different answers depending on which direction I calculated. I pulled up a free amortization tool and ran both scenarios. The difference between them was about R$ 340 in total interest over the loan term. Mental math cannot reliably handle multiple compounding variables. Use a spreadsheet or calculator whenever there are more than two moving parts. Another area where people get burned is currency conversion while traveling. Exchange rates fluctuate throughout the day and many places quote rates that include hidden margins. I once exchanged money at an airport kiosk without checking the interbank rate and lost about 4% to the spread. Checking the real rate on your phone before exchanging saved me roughly R$ 120 on a trip that year. Always compare the displayed rate against a live source before committing. None of this requires advanced mathematics. Addition, subtraction, multiplication, division, and basic percentages cover 90% of real-world situations. The remaining 10% is handled by a calculator app on your phone. What matters is developing the habit of pausing and doing the mental check before accepting a number at face value. Your future self will thank you when you are not overpaying for things you could have calculated in under a minute.

If you want to get better at this, pick one area to practice this week. Budget tracking is probably the highest-impact starting point because the numbers are concrete and the results are visible immediately. Write down every expense for seven days and categorize them. You will likely find at least one category where you can cut costs without changing your lifestyle at all. That saving then funds something you actually want, and the loop reinforces itself.
Galeria
-
Matemática No Dia A Dia | PDF | Matemática | Pedagogia -
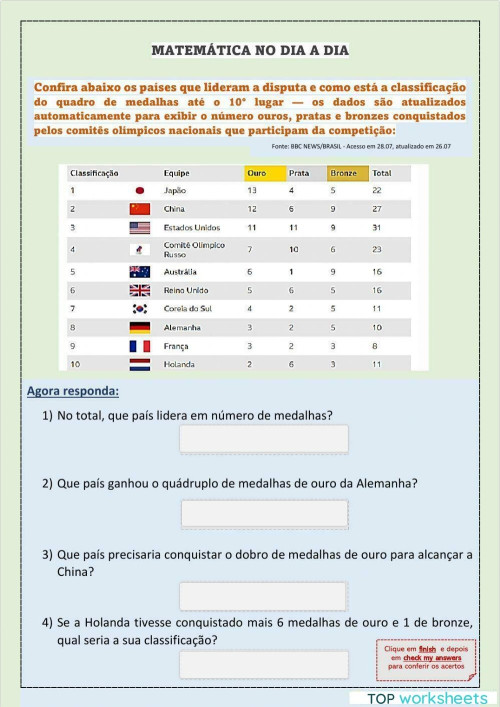
Matemática no dia a dia. Ficha interativa | TopWorksheets -
Matemática No Dia A Dia PDF | PDF


