Matematica Financeira Enem

What actually shows up on the ENEM financial math section
The ENEM doesn't ask straightforward formula-recall questions about financial math. You'll get a long contextual passage — sometimes three paragraphs — about a phone plan, a loan, a business investment, or inflation on groceries, followed by a question that asks you to pick the right rate, the final amount, or the most economical option between two scenarios. The math itself is usually simple arithmetic or basic algebra. The hard part is extracting the relevant numbers from the text and knowing which concept applies. Most students lose points because they skip steps. They see a percentage and immediately multiply without checking whether the rate is monthly or annual, or whether the time period is in months but the rate is quoted yearly. That mismatch is the #1 trap across every single edition of the exam since 2009.
matematica financeira enem
The official ENEM blueprint lists these topics under its mathematics area: simple and compound interest, percentage variation, effective versus nominal rates, currency and price index calculations, depreciation, discount operations, and expected value in probability contexts that overlap with finance. That's it. No annuities, no internal rate of return formulas, no bond pricing. If a prep book is drilling PMT or FV formulas for ENEM, it's wasting your time. I go through each question in three passes. First pass: underline every number with a unit attached — percent, real, months, years, dollar. Second pass: identify what the question is asking for and label it. Third pass: figure out which relationship connects what you have to what you need. Only then do I write a single equation. Here's a concrete example from a recent practice set that mirrors the actual exam pattern. A question described two savings plans. Plan A pays 0.5% per month in simple interest. Plan B pays 6.2% per year in compound interest. Which plan yields more after 24 months on a R$1,000 investment?
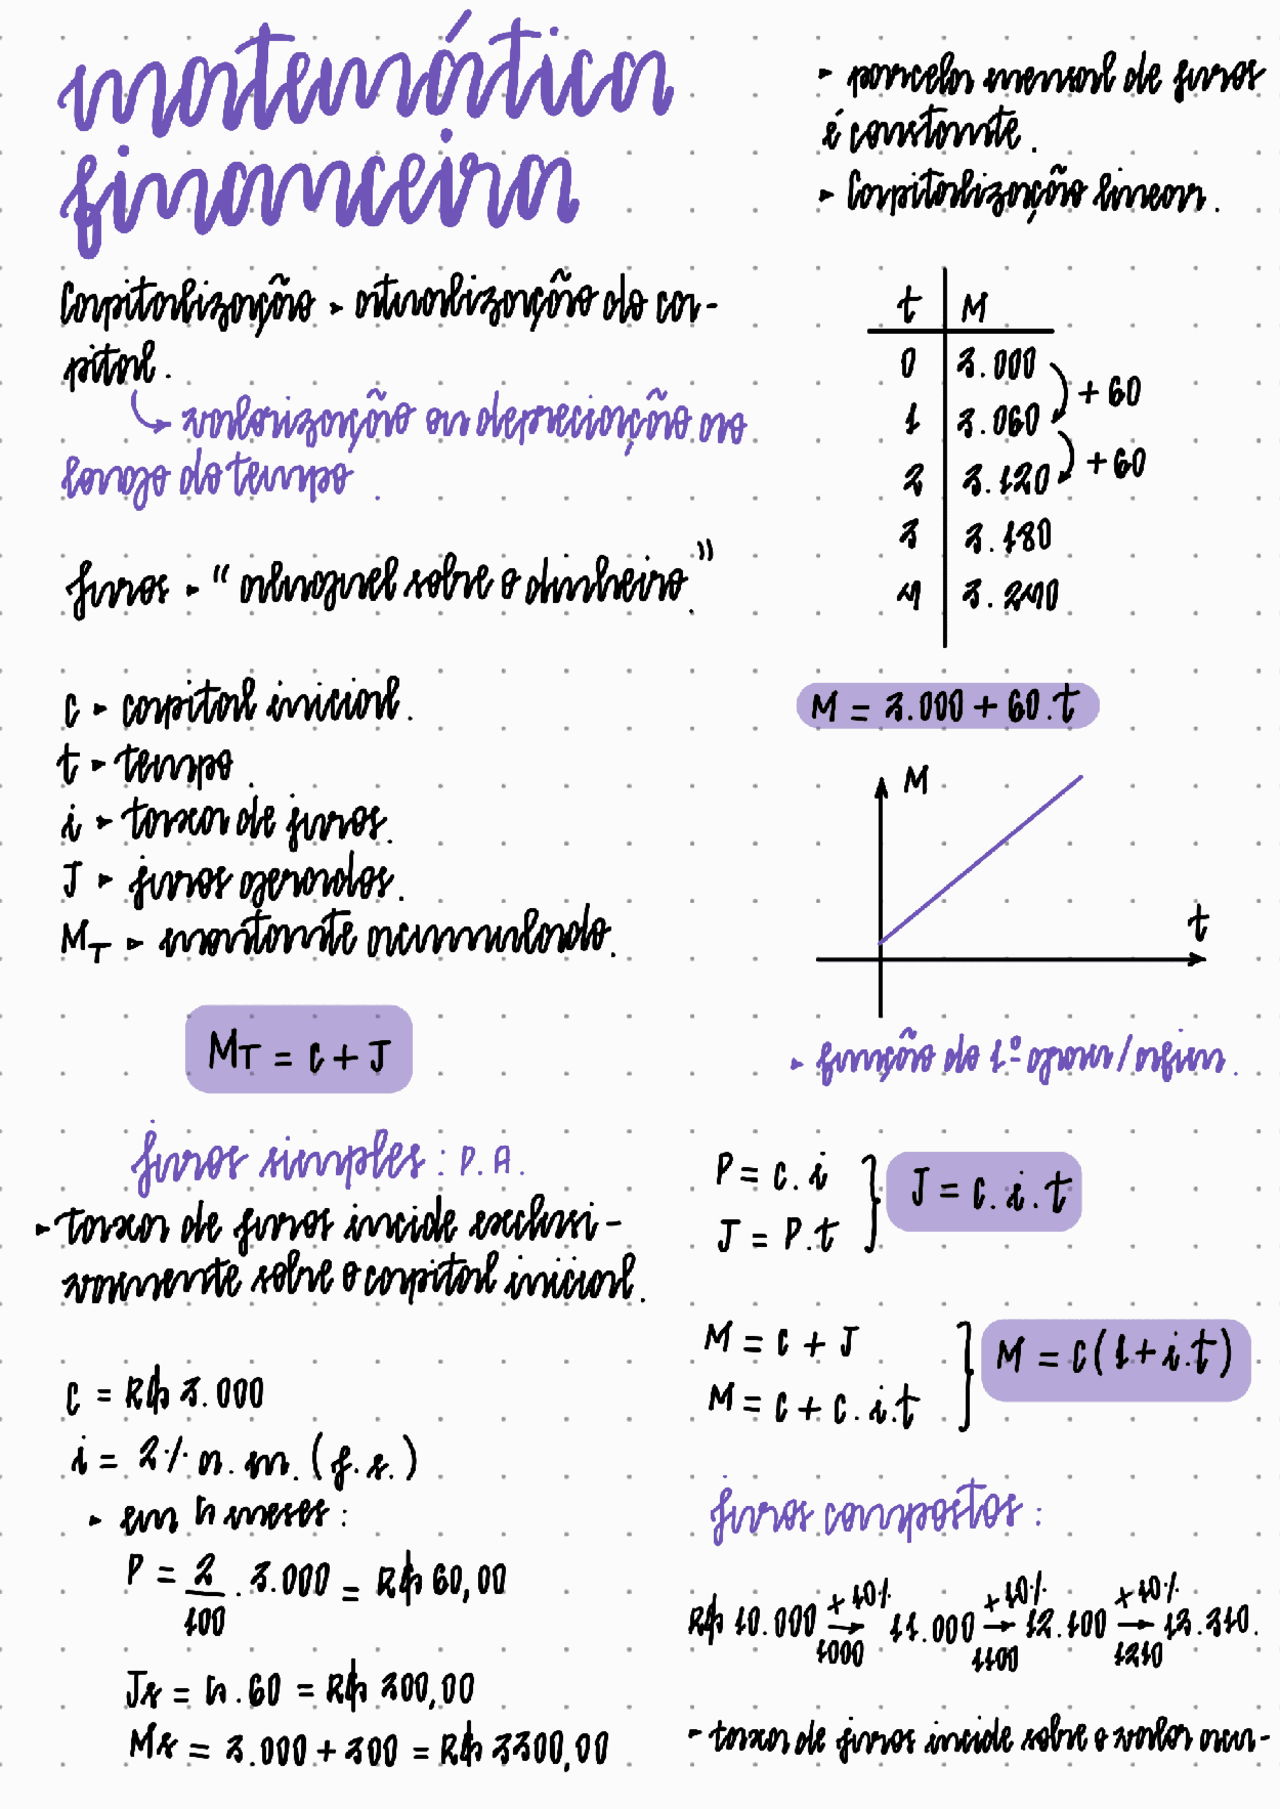
The naive approach is to just plug into two different formulas and compare. The cleaner approach is to convert everything to the same time unit first. Plan A: 0.5% × 24 months = 12% total simple interest. Final amount: R$1,120. Plan B: the annual rate is 6.2%, and 24 months is exactly 2 years. So (1.062)^2 = 1.127844. Final amount: approximately R$1,127.84. Plan B wins. The key move was converting months to years before touching any formula. This kind of question typically takes me about 90 seconds if I'm focused. Students who try to memorize which formula goes with which scenario usually take three to four minutes and still get it wrong because they picked the compound interest formula for a simple interest situation.
A specific edge case that trips people up
Last year I was reviewing old ENEM papers and encountered a question where the text gave a monthly inflation rate of 0.8% and asked for the cumulative inflation over a semester. The instinctive answer is 0.8 × 6 = 4.8%. That's wrong. The question is asking for compound cumulative inflation, not simple accumulation, because inflation compounds month to month. The correct calculation is (1.008)^6 1, which gives approximately 4.89%. The difference between 4.8% and 4.89% looks tiny, but in ENEM terms it's the difference between options C and D on the answer sheet. I learned to flag any question that mentions inflation, cumulative variation, or repeated percentage changes over multiple periods as a compound operation, even if the numbers are small. That one correction alone saved me from picking the wrong answer on at least two past exams I reviewed.
Counter-intuitive things nobody tells you
First, ENEM frequently tests the difference between nominal and effective rates without using those exact words. A question might say a bank offers "12% per year, compounded monthly" and ask for the effective monthly rate. The answer isn't 1%. It's (1.12)^(1/12) 1 0.949% per month. Students who divide by 12 automatically are selecting the nominal rate trap. Second, the exam loves to present information in tables or charts rather than sentences. You might need to read a depreciation schedule and determine whether the asset is being depreciated linearly or proportionally. Linear depreciation means equal absolute amounts each period. Proportional (or declining balance) means a fixed percentage applied to the remaining book value. Spotting the difference usually just requires checking whether the periodic decrease is constant in reais or in percentage terms.
Where the standard approach breaks down
The biggest limitation students face is time pressure. The ENEM has 180 questions in 5 hours and 30 minutes. Financial math questions are among the longer ones because of the reading required. If you spend more than two minutes on a single financial math question, you're behind. There's no workaround for slow reading speed. The only realistic fix is timed practice with a stopwatch, not additional concept review. Another genuine bottleneck: some questions combine financial math with another topic, like geometry or statistics, in a single item. You might need to calculate an average from a table and then apply a percentage change to that average. These hybrid questions don't have a standard formula. The only skill that helps is the three-pass method I mentioned earlier — identify, label, connect. Memorization doesn't apply here.

Practical resources
The official ENEM website and the Ministry of Education's portal host past exam papers with answer keys. Download the last ten editions and sort the math questions by topic. You'll notice the financial math questions appear in roughly the same positions — usually questions 130 through 160 in the blue or pink color scheme. They cluster in that range consistently, which helps with pacing during the actual exam. For study material, the free Khan Academy videos on compound interest and percentage change are adequate for building the foundation, but they don't match theENEM's contextual style. I recommend supplementing them with the Brazil School website (brasilescola.uol.com.br) for topic-specific exercises and the Estratégia Vestibulares YouTube channel for question-by-question walkthroughs of past ENEM items. Neither costs anything.
What to actually focus your time on
Master these five operations until they're automatic: converting between monthly and annual rates, calculating simple interest with mismatched time units, computing compound growth over integer periods, finding percentage increase or decrease from a table, and reading a price index chart. Everything else on the exam is a variation of one of those five. If you can do those cleanly under time pressure, the financial math section becomes manageable rather than stressful. Don't bother with advanced topics like annuity tables or amortization systems unless you have extra time after covering the basics. The ENEM hasn't asked a direct amortization calculation question in over a decade. The exam writers prefer to test whether you can reason through a financial situation, not whether you can reproduce a formula from memory.
Galeria
-
Questões de Matemática Financeira ENEM | PDF | Juros -

Minimanual de matematica financeira: enem, vestibulares e concursos -
Questões de Matemática Financeira ENEM | PDF


